Bonus depreciation lets a business deduct the full cost of most equipment and work vehicles in the year they go to work, instead of spreading it over five or seven years. Since the 2025 tax law, the full 100 percent is back, and it is permanent. This guide covers what qualifies, how trucks are treated, and when taking it all at once is the wrong move.
Greg Neilsen, JD, LLM (Master of Laws in Taxation), reviews our tax guides. Last reviewed: September 30, 2026.
Five points. Each one is explained below.
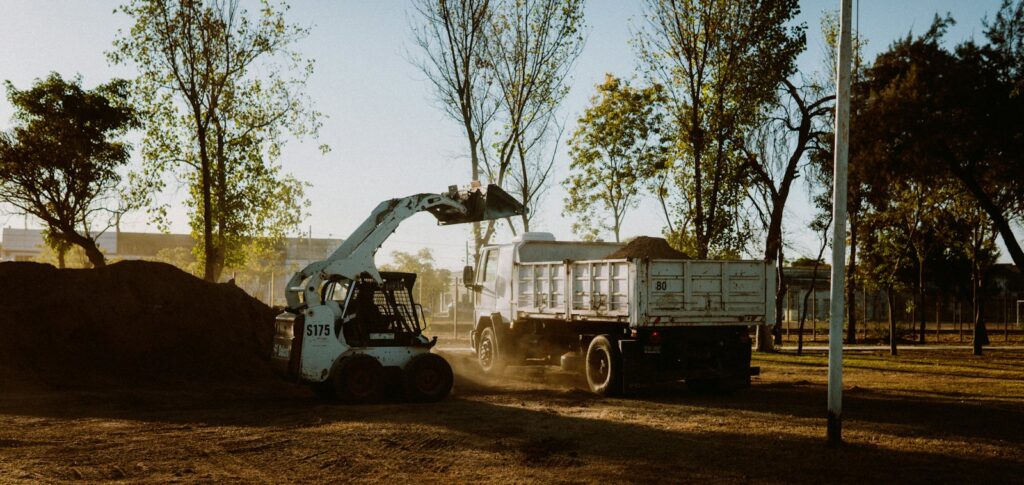
Normally, equipment is deducted a piece at a time over its tax life. Most trucks, trailers, and construction equipment have a five-year life. Bonus depreciation lets you deduct the whole cost in the first year instead.
Example: A landscaping company buys a $50,000 skid steer. Under the normal schedule, the first-year deduction is $10,000, and the rest comes over the next five years. With bonus depreciation, the full $50,000 comes off this year’s profit.
Yes, for property acquired after January 19, 2025. The 2025 tax law restored 100 percent bonus depreciation and removed the phase-down that had been cutting it each year.
Property acquired before January 20, 2025 still follows the old phase-down. The rate depends on the year it goes into service: 40 percent in 2025 and 20 percent in 2026. “Acquired” means the date you signed a binding written contract, not the delivery date.
Example: A roofer signed a binding contract for a dump truck on December 10, 2024. The truck arrived in February 2025. Because the contract came first, only 40 percent qualifies for bonus depreciation. A truck ordered on February 1, 2025 qualifies for the full 100 percent.
Most business property with a tax life of 20 years or less. For a trade or service business, that covers most of what you buy.
Used equipment qualifies too, as long as you did not use it before and you did not buy it from a related party, like a family member or another company you control.
Land and buildings do not qualify. Neither does the part of a vehicle used for personal driving.
Example: A pest control company buys a used spray rig for $18,000 from another company it has no connection to. The full $18,000 qualifies, even though the rig is not new.
Yes. Trucks and vans with a gross vehicle weight rating over 6,000 pounds are not treated as passenger cars, so the full cost can qualify. Most full-size pickups and cargo vans clear that weight. Check the sticker inside the driver’s door.
Lighter vehicles, under 6,000 pounds, are held to annual depreciation caps, even with bonus depreciation. The first-year cap is far below the price of most new vehicles.
The deduction follows business use. A truck used 90 percent for the business deducts 90 percent of its cost. Keep a mileage log. It is the first thing an examiner asks for.
Example: A roofing company buys a $72,000 pickup rated at 8,200 pounds and uses it 90 percent for work. The bonus depreciation deduction is $64,800.
Bonus depreciation is applied automatically, but you can elect out of it for a whole class of property for the year, for example all five-year property. Three situations make that worth a look.
Example: A landscaping company expects $40,000 of profit this year and $120,000 next year. It buys $90,000 of equipment. Taking all of it this year creates a $50,000 loss. Electing out spreads the deduction: $18,000 this year, and the rest over the next five years, when the same deduction is worth about twice as much per dollar.
The deduction comes back. When you sell equipment you have depreciated, the gain up to the depreciation you took is taxed as ordinary income. A trade-in counts as a sale.
Example: A plumbing company buys a $60,000 van and deducts all of it in 2026. In 2029 it sells the van for $35,000. The full $35,000 is ordinary income in 2029, because the van’s tax value was zero.
Both let you deduct equipment in the first year. Section 179 is chosen asset by asset and cannot create a loss. Bonus depreciation has no dollar limit and can. Many businesses use both. Our guide to Section 179 versus bonus depreciation compares them side by side.
Florida has no personal income tax. For S corporations, LLCs, and sole proprietors, the owner pays tax on business profit only at the federal level, so the bonus depreciation decision is federal math.
C corporations pay Florida corporate income tax, and Florida has generally required them to add bonus depreciation back and deduct it over seven years. If your business is a C corporation, check the Florida rule for your tax year before you count on the deduction.
It goes on Form 4562 with the business return. You do not have to elect it. It applies unless you elect out. Keep the invoice, the date the equipment went into service, and for vehicles, the mileage log.
Illustration only. The numbers are made up. An HVAC company buys two service vans at $55,000 each, both over 6,000 pounds, plus $12,000 of recovery machines and tools. Everything goes into service in November 2026.
The company deducts all $122,000 in 2026. At a 24 percent federal bracket, that is roughly $29,000 less tax this year. If next year looks much bigger, we would compare electing out for one class of property.
More on how we work with HVAC companies.
In our Planned plan, the written tax plan covers equipment: what to buy, when to put it in service, and whether to take bonus depreciation or spread it out. We run the numbers before you sign, not after.
Read the year-end tax planning checklist, or see how this works for roofing and landscaping companies.
Yes, at 100 percent, for property acquired after January 19, 2025. The 2025 tax law made it permanent. Property acquired earlier follows the old phase-down.
Yes, as long as you did not use the equipment before and you did not buy it from a related party.
Not to the building itself. It can apply to parts of a rental property with shorter tax lives, like appliances, carpet, and some outdoor improvements. A cost segregation study identifies those parts.
Yes. Unlike Section 179, bonus depreciation can push the business into a loss. The loss carries forward to future years, with limits on how much it can offset each year.
No. It applies automatically. If you do not want it, you elect out on the return, for a whole class of property, for that year.
This guide is educational and is not tax advice for your situation. Tax rules change, and the right move depends on your numbers. Talk to a tax professional before you act.
Greg Neilsen, JD, LLM (Master of Laws in Taxation), reviews our tax guides. Last reviewed: September 30, 2026.
One free 15-minute call with Greg. Bring your questions. Leave knowing what Zero Tax would handle for your business and what it would cost.
Book a free 15-minute callNo pressure, no obligation. Just clarity.